Inventory Management for Small Retail Stores: A Practical Guide
A practical inventory management system for small U.S. retailers: SKUs, reorder points, cycle counts, cash flow, stockouts and slow-moving items.
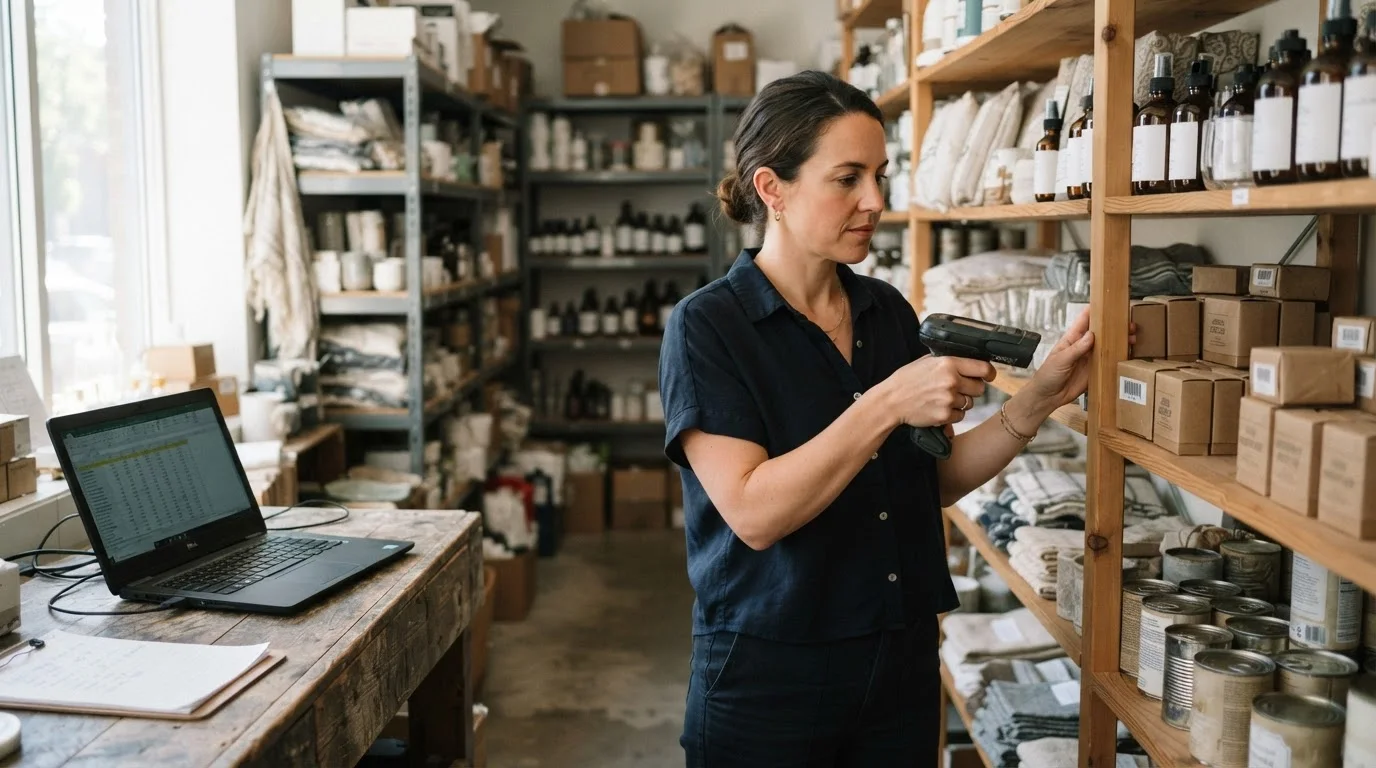
Inventory management for small retail stores is the process of knowing what you have, where it is, how quickly it sells, and when to reorder without tying up money in products that sit on shelves. A shop can show strong sales and still face a cash shortage because its bestsellers are out of stock while slow-moving items consume available capital.
This practical U.S. retailer guide covers SKUs, daily stock movement, cycle counts, reorder points, safety stock, inventory turnover and a simple spreadsheet workflow. All dollar figures and store examples are illustrative teaching scenarios, not measured industry averages. Reviewed October 27, 2026.
Quick answer: Give every variant a unique SKU, record receipts and sales, count high-value or fast-moving items frequently, calculate a reorder point from actual demand and supplier lead time, and review dead stock and cash tied up in inventory each month.
Why inventory accuracy matters more than having a full storeroom
Inventory problems have opposite but related costs: a stockout sends customers elsewhere; overstock locks money in merchandise you cannot use to pay payroll or suppliers. Shrinkage from damage, miscounts, theft and administrative errors makes system stock differ from physical stock. Each discrepancy affects buying, margins, customer trust or tax records.
The IRS Publication 334: Tax Guide for Small Business explains that businesses carrying merchandise generally must account for inventory and cost of goods sold under applicable tax rules, although permitted small-business methods and exceptions vary. Ask a qualified accountant about your specific entity and accounting method; the operational counts in this guide do not replace tax accounting.
The seven fields every product should have
| Field | Example | Why it matters |
|---|---|---|
| SKU | CANDLE-8OZ-VAN | Unique variant identifier |
| Product / variant | 8 oz vanilla candle | Distinguishes products |
| On-hand quantity | 22 units | Counted available units |
| Unit landed cost | $9.50 | Purchase plus attributable inbound cost |
| Selling price | $24 | Retail offer, not profit |
| Supplier lead time | 12 calendar days | Expected replenishment delay |
| Reorder point | 21 units | When to review and place an order |
The numbers above are fictional. Add storage location, preferred supplier, purchase-order number, expiration date or batch/lot where relevant, minimum order quantity, and whether units are reserved for pending orders. Use the same SKU across point-of-sale, e-commerce and your inventory file.
Build a retail inventory system in five steps
1. Create a single product list with a SKU for each variant
A blue medium T-shirt and a blue large T-shirt are separate SKUs because demand and availability differ. If you sell online and in person, do not maintain conflicting stock counts on independent sheets. Decide which system is the source of truth, and log transfers and returns explicitly.
2. Establish an opening physical count
Count units in the store and back room before trusting your point-of-sale balance. Exclude damaged, expired or customer-reserved items from available-to-sell stock as appropriate. Have one person count and another review expensive items when staffing allows. Record the time of the count, because purchases or sales afterward change the result.
3. Record each inventory movement
- Receiving: supplier shipment, quantity received, cost and exceptions.
- Sales: units sold, by SKU and channel.
- Returns: restockable and unsellable units separately.
- Adjustments: damage, theft, giveaways and counting corrections with reasons.
- Transfers: movement between shelf, storage room or locations without treating it as a sale.
4. Schedule cycle counts
Instead of shutting the store to count everything once a year, count a small set of products regularly and investigate discrepancies. A simple ABC approach gives the most attention to inventory with the greatest sales value or risk. ABC categories are management priorities, not a reason to ignore the rest of the stock.
5. Review demand, supplier performance and cash
Every week, review out-of-stock SKUs, late purchase orders and products with unexpected selling patterns. Monthly, review inventory age, gross margin, cash tied up in stock, and how demand differs from your forecast. Use facts from your own shop rather than adopting a generic replenishment percentage.
Reorder point formula for small retail stores
Reorder point = average daily unit demand × replenishment lead time + safety stock. Suppose a candle sells 2 units per day, a supplier usually takes 7 days to deliver, and the shop decides to carry 6 additional units of safety stock. The illustrative reorder point is 2 × 7 + 6 = 20 units. Review and reorder when inventory position reaches approximately 20 units.
If the supplier actually takes 12 days, the same assumptions produce 2 × 12 + 6 = 30 units. This illustrates why ordering by intuition fails when lead times change. Inventory position should account for stock on hand plus units already ordered minus outstanding customer commitments; use a consistent definition.
How much should you reorder?
The reorder point signals when to buy, not automatically how many to buy. For a modest fixed-target system, choose a target stock level based on forecast demand, review frequency, lead time and desired buffer, then subtract inventory position. Check supplier minimums, case packs, shelf capacity, discounts and cash before placing the order.
Safety stock: protect availability without overbuying
Safety stock helps absorb demand variability or late shipments, but it has a carrying cost. A simplistic fixed buffer may be sufficient for a small shop during an initial test; with more reliable history, calculate buffers from variations in daily demand and supplier lead time. Separate seasonal products and perishables from steady sellers.
For example, if a supplier routinely arrives later than promised during November, adjust assumptions based on recorded delays rather than treating the current seven-day lead time as fixed all year. Do not use a larger buffer as a substitute for resolving unreliable suppliers.
Inventory turnover and days of inventory
Inventory turnover = cost of goods sold ÷ average inventory at cost. If annual COGS is a hypothetical $90,000 and average inventory at cost is $15,000, turnover is 6 times a year. Estimated days of inventory = 365 ÷ 6 = approximately 61 days. Compare similar product types and periods; a grocery’s expectations differ from those of furniture or fine jewelry.
Neither a high nor low turnover automatically proves success. Extremely high turnover may mean regular stockouts, while low turnover can be appropriate for specialty goods—but can also indicate unsold products. Pair turnover with stockout frequency, gross margin, age, supplier reliability and cash flow.
A practical ABC classification example
| Category | Illustrative rule | Count frequency | Purchasing review |
|---|---|---|---|
| A | Highest-value or most important SKUs | Weekly | Demand, service level, lead time |
| B | Moderate contribution SKUs | Monthly | Sales trend and batch sizing |
| C | Lower-value or low-risk SKUs | Quarterly | Simpler replenishment with spot checks |
These frequencies are suggested starting points for a small team, not an official required standard. Theft-sensitive, high-risk, perishable or regulated products may require more frequent checks regardless of value.
A small-store inventory audit you can run this Friday
| Check | Question | Action |
|---|---|---|
| Physical count | Do the shelf and system quantities match? | Count selected A items and investigate variances |
| Open purchase orders | Which orders are late or partial? | Contact suppliers and update ETA |
| Stockouts | Which items disappointed customers? | Record demand lost and adjust reorder review |
| Slow movers | Which units have sat for 90+ days? | Check margins and realistic markdown options |
| Returns | How many items cannot be resold? | Separate sellable from damaged stock |
| Cash | Can upcoming bills be paid after reordering? | Use the cash forecast before buying |
Dead stock and markdowns: calculate before discounting
Suppose 40 old phone cases cost a store $8 each, or $320 in tied-up merchandise. A markdown to $10 each might recover up to $400 in sales before transaction fees, selling costs and taxes if every unit sells. A discount is not guaranteed recovery: some units may remain unsold. Consider bundles, measured discounts, returns to the vendor where permitted, or donation when appropriate, and record stock adjustments correctly.
A better lesson is to trace why these cases became obsolete. Perhaps the shop ordered too many color variants, ignored declining sales, or bought a discounted case pack without examining demand. A future purchase order should reflect that evidence.
Managing inventory across a physical shop and online
If the same item is listed on your website and sold at the register, a real-time stock connection—or a disciplined reservation and reconciliation workflow—is important. Otherwise the final available unit can be sold twice. Monitor returns, exchanges, fulfillment delays, and payment disputes. Keep safety stock realistic rather than hiding all available inventory from customers.
When is software worth paying for?
A spreadsheet may be sufficient for a store with a small number of SKUs, limited transactions and one location if staff follow a clear process. Software becomes valuable when transaction volume, multiple locations, online channels, supplier catalogs or staff permissions create too much manual work. Before paying, test barcode scanning, offline behavior, integration with your POS, purchase-order receiving, user roles, export capability and the true monthly price.
A useful upgrade test: estimate how many staff hours accurate software would save, what stockouts or errors it could prevent, and whether those measurable benefits exceed subscription and implementation costs. Never assume a feature-rich system will solve poor receiving habits on its own.
Inventory planning and working capital belong together
Ordering too much can make a business cash-poor even when shelves look full. Use our free small-business cash flow forecast template to see how a purchase order affects the next 13 weeks. Also review seasonal inventory purchasing, retail product profitability and working capital for small businesses.
30-day inventory reset plan
- Week 1: define SKUs, assign ownership, perform an opening spot count and record variances.
- Week 2: review sales and supplier lead times for your 20 most important items; create reorder points.
- Week 3: establish receiving and returns rules, assess products with no recent sales, and check purchase commitments against cash.
- Week 4: compare counts with the system, investigate discrepancies, review what sold out, and revise ordering rules.
Frequently asked questions
What is the best inventory management method for a small store?
A consistent SKU list, timely transaction records, cycle counts and demand-based reorder rules provide a practical foundation. The best software or manual approach depends on sales volume, channels, number of items and staff.
What is the difference between inventory on hand and inventory available?
On hand means physically held, while available typically subtracts units reserved or otherwise unavailable for sale. Inventory position for reordering can also include confirmed incoming units. Define each number consistently across the store.
How do I calculate a reorder point?
Multiply average unit sales per day by expected replenishment lead time and add a suitable buffer. For example, 2 units/day × 7 days + 6 safety units = 20 units. Revisit the inputs as demand or deliveries change.
How often should I count retail inventory?
Frequency depends on risk and volume. Count high-value or high-velocity items more often and rotate through lower-risk products. You may also need full physical inventories for operational or accounting reasons.
How do I reduce overstock without hurting margins?
Identify slow-moving variants early, lower purchase quantities, avoid misleading bulk discounts, verify demand before replenishing and measure the real recovery from any markdown. Do not automatically cut prices on healthy bestsellers.
Does inventory equal cash?
No. Merchandise recorded as an asset cannot pay bills until it sells and the customer payment clears. Slow-moving stock may ultimately sell below cost or become unsellable.
Is an inventory management app required by the IRS?
No single app is required by the IRS. Your records and method must comply with relevant rules. Ask a tax professional how inventory, cost of goods sold and record retention apply to your business.
Sources and editorial methodology
Reviewed October 27, 2026. The methods and definitions in this guide are grounded in business accounting principles and established retail inventory practices. All example SKUs, demand values, lead times, purchase costs, margins and 30-day planning targets are invented teaching scenarios; they are not national statistics or supplier prices.